


Introduction to the Different Types of Income
Income is more than just the salary you receive from a job. It can also come from investments, businesses, rental properties, royalties, and other sources. Some types of income require active work, while others can keep generating earnings with limited ongoing involvement.
Understanding the different types of income can help you diversify your earnings, make informed financial decisions, plan investments, and understand potential tax implications.
For example, a salaried employee may earn active income from their job, interest from bank deposits, dividends from shares, and rental income from property. Each source has different characteristics, risks, and tax considerations.
In this article, we explore 11 types of income, with definitions, real-life examples, advantages, and limitations to help you understand how different income sources contribute to financial stability.
Table of Contents
Top 11 Types of Income
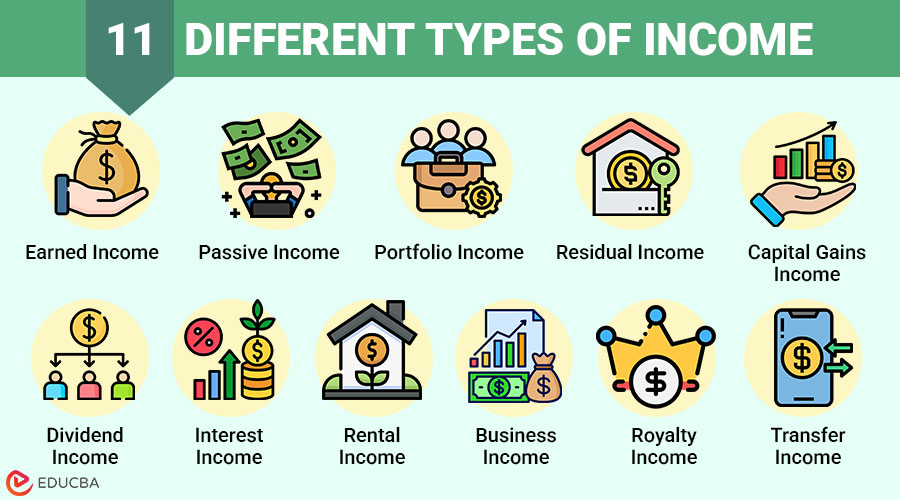
Here are the 11 major types of income that can help you build financial security and independence:
| Type of Income | Main Source | Example |
| Earned Income | Employment or active work | Salary, wages, freelancing |
| Passive Income | Investments or activities requiring limited ongoing involvement | Rental property, certain digital products |
| Portfolio Income | Financial investments | Dividends, interest, capital gains |
| Residual Income | Ongoing earnings from previous work | Online courses, book royalties |
| Capital Gains Income | Selling assets for a profit | Selling shares or property |
| Dividend Income | Distributions from investments | Company dividends |
| Interest Income | Lending or depositing money | Fixed deposits, bonds |
| Rental Income | Leasing assets | House rent, equipment rentals |
| Business Income | Business operations | Profits from a retail store |
| Royalty Income | Intellectual property licensing | Books, music, software |
| Transfer Income | Transfers without current goods or services provided in return | Government benefits, certain pensions |
#1. Earned Income (Active Income)
Earned income is money you receive by actively working, either as an employee or through self-employment. It requires your time, effort, and skills.
Examples:
- Full-time job: A software engineer earns ₹10,00,000 annually through salary.
- Freelancing: A graphic designer earns by taking up client projects online.
- Business owner (active): A bakery owner who manages daily operations earns income through daily sales.
Advantages:
- Salaried employment can provide predictable and regular cash flow.
- A documented income history may help individuals qualify for loans and other financial products.
- Professional development and experience can create opportunities for higher earnings.
Limitations:
- Earnings generally depend on continued employment or active work.
- Income growth may be limited by available working hours or salary structures.
- Earnings may be subject to progressive income tax rates, depending on the jurisdiction.
#2. Passive Income
You earn passive income from activities or investments that need little ongoing effort after the initial setup and investment.
Examples:
- Rental properties: Buying an apartment and renting it out monthly.
- YouTube channel: Earning ad revenue from old videos.
- Dropshipping or affiliate marketing: Automated online businesses that earn without day-to-day involvement.
Advantages:
- Can provide an additional income stream alongside regular employment.
- Some passive income sources can continue generating earnings over time.
- May help diversify income sources and reduce dependence on a single job.
Limitations:
- Often requires substantial initial capital, time, or specialized skills.
- Earnings may be irregular and depend on market demand.
- Ongoing maintenance, promotion, management, or monitoring may still be necessary.
#3. Portfolio Income (Investment Income)
Income comes from the growth or returns you earn on financial investments like stocks, bonds, or mutual funds.
Examples:
- Capital gains: Selling stocks for more money than you paid for them.
- Dividends: Receiving quarterly payments from shares of a profitable company.
- Mutual fund withdrawals: Gaining returns from SIPs or lump-sum investments.
Advantages:
- Offers opportunities for long-term wealth accumulation.
- Reinvested earnings may contribute to compounding.
- Helps diversify income beyond employment or business activities.
Limitations:
- Investment values and returns are subject to market risks.
- Dividends and capital gains are not guaranteed.
- Tax treatment depends on the investment type, holding period, and applicable laws.
#4. Residual Income
Residual income refers to money earned on an ongoing basis for work completed in the past.
Examples:
- Online course: A teacher creates a course once and earns money each time someone buys it.
- eBooks: Royalties from book sales on platforms like Amazon Kindle.
- Software licenses: A developer earns from selling usage rights repeatedly.
Advantages:
- Can generate recurring earnings from earlier work.
- Certain digital products can reach customers across different markets.
- May provide opportunities to scale earnings without repeating the entire creation process.
Limitations:
- Earnings depend on customer demand and product relevance.
- Products may require updates, maintenance, or continued marketing.
- Recurring income can decline due to competition or changing consumer preferences.
#5. Capital Gains Income
Capital gains are profits from selling capital assets like real estate, stocks, or other valuable assets.
Examples:
- Real estate flip: Buying land at ₹20 lakhs and selling it for ₹35 lakhs.
- Stock market: Purchasing shares at ₹500 each and selling them at ₹750.
- Crypto: Earning profit from trading digital assets like Bitcoin.
Short-Term vs. Long-Term Capital Gains:
- Short-Term: Taxed at higher rates, often like earned income.
- Long-Term: Enjoys lower tax rates; encourages long-term investment.
Advantages:
- Offers opportunities to profit from increases in asset values.
- Can contribute to long-term wealth creation.
- Some jurisdictions provide specific tax treatments for eligible capital gains.
Limitations:
- Asset values can decline, resulting in capital losses.
- Gains may be subject to taxes, transaction costs, and reporting requirements.
- Market timing and investment decisions involve uncertainty.
#6. Dividend Income
Dividend income is money you earn from a company when it shares part of its profits with its shareholders.
Examples:
- Blue-chip stocks: Companies like TCS, Infosys, or Reliance pay consistent dividends.
- REITs: Real Estate Investment Trusts that distribute earnings from rent collections.
Advantages:
- Can provide investment income without selling shares.
- Reinvesting dividends may support long-term compounding.
- May supplement other sources of income.
Limitations:
- Dividends are not guaranteed and may be reduced or discontinued.
- Share prices can decline even when dividends are paid.
- Dividend income may be taxable depending on the jurisdiction.
#7. Interest Income
Interest income is money earned by lending your money or depositing it in interest-generating instruments.
Examples:
- Fixed deposits (FDs): Banks pay interest for locking in funds.
- Savings account: Though low, banks offer a fixed interest rate.
- Bonds: Government or corporate bonds pay periodic interest to investors.
Advantages:
- Some interest-bearing products provide relatively predictable earnings.
- Bank deposits and certain government securities may have comparatively lower risk.
- Can be useful for individuals seeking income or capital preservation.
Limitations:
- Interest rates may not keep pace with inflation.
- Interest income may be taxable.
- Corporate bonds carry credit risk, and bond prices can fluctuate with market interest rates.
#8. Rental Income
You earn rental income by leasing out property, vehicles, or equipment.
Examples:
- Residential units: Monthly rent from tenants.
- Commercial buildings: Leasing office spaces to businesses.
- Equipment rentals: Renting out projectors, cameras, or vehicles.
Advantages:
- Can provide recurring cash flow.
- Some assets may appreciate over time.
- Eligible expenses and deductions may offer tax benefits under applicable laws.
Limitations:
- Owning property and buying equipment may require substantial capital.
- Vacancies, repairs, insurance, and maintenance can reduce net earnings.
- Tenant management and regulatory compliance may require ongoing attention.
#9. Business Income
Profits are generated by running a business, either as an entrepreneur or a silent partner.
Examples:
- Retail store: Earnings after deducting the costs of goods and operations.
- Online store: Net income from product sales through e-commerce platforms.
- Consulting firm: Revenue from offering expert advice.
Advantages:
- Offers opportunities for business expansion and income growth.
- Entrepreneurs may have greater control over business decisions.
- Successful businesses can create additional jobs and attract investment.
Limitations:
- Business owners face financial and operational risks.
- Revenue does not always translate into profit.
- Managing operations, employees, customers, and compliance can require substantial time and effort.
#10. Royalty Income
Royalties are payments given to people who create or own something, like a book or song, when others use it.
Examples:
- Authors: Royalties from published books.
- Musicians: Royalties from streaming platforms like Spotify or Apple Music.
- Software: Licensing custom software to companies.
Advantages:
- Can generate income from intellectual property over an extended period.
- The same intellectual property may be licensed through multiple channels.
- Offers opportunities to monetize creative and technical work.
Limitations:
- Income depends on licensing arrangements, usage, and market demand.
- Intellectual property protection and contract management can be complex.
- Royalty payments may fluctuate or decline over time.
#11. Transfer Income (Government Benefits)
Transfer income is received without a direct exchange of goods or services, often funded by public programs or court orders.
Examples:
- Pensions: Monthly income after retirement from government or private schemes.
- Social welfare: Benefits for unemployment, disability, or low income.
- Scholarships: Educational funds awarded based on merit or need.
Advantages:
- Can provide financial assistance during unemployment, retirement, disability, or other periods of need.
- Helps eligible individuals meet essential expenses.
- Certain programs contribute to broader social and economic stability.
Limitations:
- Eligibility requirements may restrict access.
- Payment amounts and program availability may change.
- Tax treatment varies depending on the payment type and jurisdiction.
Why Understanding Types of Income Matters?
Understanding income sources is an important part of personal financial planning. It can help individuals evaluate earning opportunities, manage financial risks, and make informed decisions.
- Better Financial Planning: Knowing where your income comes from helps you estimate cash flow, prepare budgets, build emergency savings, and plan for future expenses.
- Income Diversification: Depending entirely on one income source can create financial vulnerability. Additional income from investments, rentals, or business activities may reduce dependence on a single source, although diversification does not eliminate financial risk.
- Smarter Tax Planning: Different income sources may be subject to different tax rules. Understanding these differences can help individuals maintain accurate records, identify eligible deductions, and plan their tax obligations.
- Informed Investment Decisions: Recognizing the differences between interest, dividends, capital gains, and rental earnings can help investors evaluate potential returns, risks, liquidity needs, and investment horizons.
- Long-Term Financial Stability: Combining appropriate income sources with budgeting, saving, and responsible investing may strengthen financial resilience and support long-term goals.
Final Thoughts
Understanding the 11 different types of income can help you recognize opportunities beyond traditional employment. From salaries and business profits to dividends, interest, rental earnings, and royalties, each income source offers different benefits, responsibilities, and risks.
Building multiple income streams may support financial stability, but successful financial planning also requires careful budgeting, risk management, and an understanding of applicable tax rules.
Start by identifying your existing income sources and evaluating which additional opportunities align with your financial goals, available resources, and risk tolerance.
Frequently Asked Questions (FAQs)
Q1. What are the main types of income?
Answer: Income is often broadly grouped into earned income, portfolio income, and passive income. More specific sources include salaries, business profits, interest, dividends, capital gains, rent, royalties, and transfer payments. These classifications can overlap.
Q2. What is the difference between active and passive income?
Answer: Active income generally requires ongoing work, such as employment or freelancing. Passive income comes from investments or activities that may require less ongoing involvement after an initial investment of time, effort, or money. However, passive income can still require management and maintenance.
Q3. Which types of income can help build long-term wealth?
Answer: Earned income, business income, dividends, interest, capital gains, and rental income can all contribute to long-term wealth creation. Their suitability depends on financial goals, risk tolerance, available capital, and investment time horizon.
Q4. Can a person earn multiple types of income simultaneously?
Answer: Yes. For example, an employee may receive a salary, earn interest from fixed deposits, collect dividends from shares, and receive rent from property. Having multiple sources may improve income diversification.
Q5. Are all types of income taxable?
Answer: Not necessarily. Tax treatment depends on the income source, the taxpayer’s circumstances, and applicable laws. Some income may be taxable, exempt, or subject to special rules. Individuals should consult the relevant tax regulations or a qualified tax professional for jurisdiction-specific guidance.
Recommended Articles
We hope this guide on types of income helps you diversify your earnings and make more informed financial choices. The recommended articles below offer further strategies to strengthen your financial foundation, boost passive income, and grow long-term wealth:


