

Full Form of KYC
KYC, full form “Know Your Customer“, is used to identify and verify the identity of customers before opening a bank account. It also helps assess an individual’s risk of financial fraud. The KYC process involves collecting and verifying certain personal information. This includes your name, address, and identification documents such as your Aadhaar and PAN cards. The report verifies your identity. It also helps ensure you are not involved in any illegal activities. If you refuse to provide KYC documents, the bank may not be able to open an account for you.
Even e-wallets like Paytm now require KYC. If you have a KYC-compliant bank account, you don’t need to submit your documents again when opening another account with the same bank. You will also need KYC to use credit or debit cards. Customers without bank accounts must provide proof of identity and address when purchasing third-party products from banks if the transaction is Rs.50,000 or more. KYC exercise may be optional for the bank’s customers when purchasing third-party products. However, in some instances, this may apply only sometimes. These cases include instructions to debit customers’ accounts for payments.
Another instance is making payments against cheques for fund remittances. It also applies to issuing travelers’ cheques and selling gold/silver/platinum. You also need to quote your PAN number for transactions of Rs.50,000 and above, whether you are a regular customer or a walk-in customer.
Table of Contents
- Full Form of KYC
- What is KYC?
- Why is KYC Important?
- The History of Financial Laws in India
- What are the Types of KYC?
- How Does the KYC Process Work?
- Difference Between KYC and e-KYC
- What Do Banks Need to Do?
- Do I Need KYC for My Business?
- Benefits of KYC
Key Takeaways
- The full form of KYC is Know Your Customer, a process used to verify customers’ identities and addresses.
- KYC helps prevent financial fraud, identity theft, money laundering, and other illegal activities.
- KYC methods include online and offline, Aadhaar-based e-KYC, video-based verification, and centralized KYC (CKYC).
- Customers must provide valid identity and address proof documents, depending on the financial service and applicable regulations.
- KYC helps financial institutions meet regulatory requirements and keep financial transactions secure.
- Customers can complete KYC online or offline, depending on the verification methods their bank or service provider offers.
What is KYC?
The full form of KYC is “Know Your Customer.” Financial institutions, such as banks, use it to verify customers’ identities.
Hence, it is aptly called “Know Your Customer.” It helps combat financial fraud, terrorist financing, and money laundering. It ensures compliance with various laws and regulations. These include India’s Prevention of Money Laundering Act (PMLA) and the Foreign Exchange Management Act (FEMA).
Example: Opening a Bank Account
Suppose Rahul wants to open a savings account at a bank. The bank asks him to provide personal details and accepted proof of identity and address, such as his PAN and other officially accepted documents. The bank verifies his information before approving the account.
If Rahul completes the required checks successfully, the bank can proceed with opening his account, subject to its requirements. This process is known as KYC (Know Your Customer). It helps the bank confirm Rahul’s identity and reduce fraud risk.
Why is KYC Important?
KYC (Know Your Customer) helps financial institutions verify customers’ identities, prevent financial fraud, and comply with legal requirements. It creates a safer environment for banking and other financial transactions.
- Identity Verification: KYC helps banks and financial institutions confirm a customer’s identity and address using valid documents. This process ensures that the person opening an account or accessing financial services provides accurate information.
- Fraud Prevention: KYC helps reduce the risk of identity theft, fake accounts, and other financial crimes. By verifying customer details, financial institutions can identify suspicious activities and take appropriate action.
- Regulatory Compliance: Financial institutions must follow applicable KYC rules and regulations. In India, the RBI issues KYC directions for regulated entities to help prevent money laundering and terrorist financing. Following these requirements also helps institutions maintain proper customer records.
- Secure Financial Transactions: KYC supports safer banking, money transfers, and other financial activities by helping institutions understand who their customers are and assess potential risks.
- Building Trust: A proper KYC process helps create a more reliable financial system. It supports transparency between customers and financial institutions while reducing opportunities for misuse of financial services.
The History of Financial Laws in India: KYC Edition
KYC originated in response to serious crimes, including terrorist financing. International KYC regulations aim to prevent these activities and help financial institutions, such as banks, detect them. KYC, or Know Your Customer, is also legally required in India.
In the early 2000s, the Reserve Bank of India made it compulsory for all Indian financial institutions to verify customer details. This included verifying the identity and address of all customers conducting financial transactions. The RBI introduced KYC, or Know Your Customer, as the only method for this verification. As mentioned, it prevents crimes like money laundering and terrorist financing.
What Are the Types of KYC?
KYC methods are classified as offline, online, and centralized systems. In India, financial institutions use these methods to verify customers’ identities and addresses based on the service and applicable regulations.
Main Types of KYC:
- Aadhaar-Based e-KYC: Aadhaar-based electronic KYC uses permitted Aadhaar authentication or verification methods to confirm a customer’s identity digitally. Depending on the method, it may use an OTP or biometric authentication, subject to applicable rules and customer consent.
- Offline KYC: Offline KYC allows customers to verify their identity by submitting or presenting accepted documents without relying on real-time Aadhaar authentication. The process may involve physical documents or digitally verifiable identity information.
- Video-Based KYC (V-CIP): Video-based KYC allows eligible financial institutions to verify customers remotely through a secure video interaction. An authorized representative checks the customer’s identity and documents according to the institution’s verification procedures and applicable RBI guidelines.
- In-Person KYC: In-person KYC involves visiting a bank branch or an authorized service location to complete identity verification. Customers may need to present original documents or provide copies of accepted identity and address proofs.
- Central KYC (CKYC): Central KYC allows customer KYC records to be maintained in a centralized registry called the Central KYC Records Registry (CKYCR). After completing the required process, eligible customers receive a 14-digit KYC identifier that participating financial institutions may use to retrieve their records, subject to applicable requirements.
KYC methods vary by institution, service, and regulations. Check with your bank to confirm which options are available.
How Does the KYC Process Work?
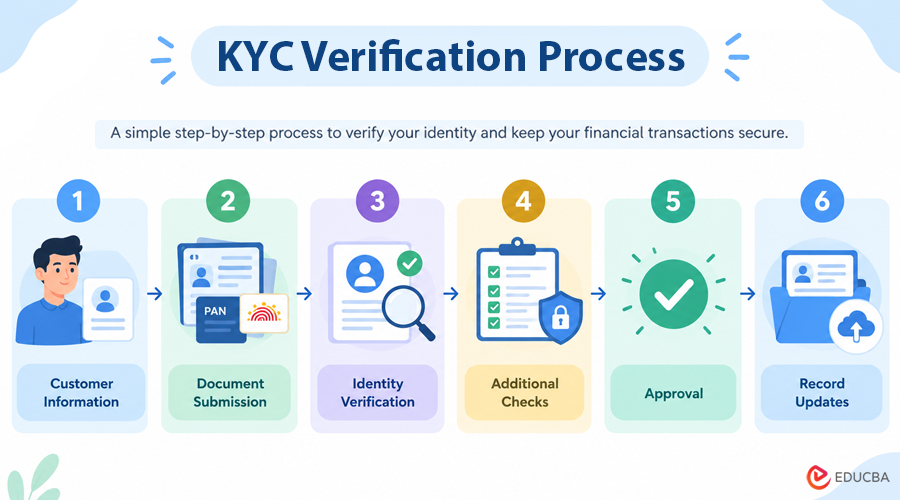
The KYC process involves the following steps to verify a customer’s identity and address:
- Customer Information: The customer provides personal details, such as their full name, date of birth, address, and contact information.
- Document Submission: The customer submits the required identity and address proof documents, such as a passport, driving license, or other accepted documents.
- Identity Verification: The bank or financial institution checks the submitted information and documents to confirm the customer’s identity.
- Additional Verification: Depending on the method, the institution may use OTP authentication, biometric verification, or video-based verification to confirm the customer’s details.
- KYC Approval: Once the institution completes the necessary checks, it approves the KYC if the customer meets the applicable requirements. If any information is missing or unclear, the customer may need to provide additional details.
- Record Maintenance and Updates: The institution maintains the customer’s KYC records and requests updates when required under applicable regulations.
Customers can complete KYC online or offline, depending on the options offered by their bank or financial service provider.
What is the Difference Between KYC and e-KYC?
KYC (Know Your Customer) verifies a customer’s identity and address, while e-KYC (Electronic Know Your Customer) uses electronic methods to complete the verification.
| Basis | KYC | e-KYC |
| Meaning | Know Your Customer | Electronic Know Your Customer |
| Process | May involve physical documents or digital methods | Uses electronic verification methods |
| Verification | May require in-person checks | Can be completed remotely, depending on the method |
| Time | May take longer if manual checks are required | Often faster through digital systems |
| Documents | May require physical or digital documents | Uses electronic records or digital document verification |
| Convenience | May require a branch visit | Can often be completed online |
| Example | Submitting documents at a bank branch | Completing permitted electronic identity verification |
Both KYC and e-KYC help prevent identity fraud and support regulatory compliance. The available method depends on the financial institution, the service, and applicable rules.
What Do Banks Need to Do?
The Reserve Bank of India (RBI) has issued guidelines for financial institutions to implement KYC norms. These guidelines require banks to collect and verify certain customer information, as mentioned above. Banks must also maintain records of all customer transactions and update them periodically. This way, banks can detect suspicious transactions.
Do I Need KYC for My Business?
Financial institutions, such as banks, typically carry out the KYC process. However, other businesses and individuals should also understand the process, as they may be subject to KYC requirements. Companies engaged in financial transactions, such as money transfer services and money changers, must also comply with KYC requirements. In addition, individuals involved in financial transactions, such as buying or selling property or investing in securities, must also comply with KYC requirements.
Benefits of KYC
KYC offers several benefits to customers and financial institutions by improving security and ensuring proper identity verification.
Key Benefits
- Fraud Prevention: Helps reduce identity theft, fake accounts, and financial fraud.
- Regulatory Compliance: Helps financial institutions follow applicable laws and regulations.
- Secure Transactions: Supports safer banking, money transfers, and other financial activities.
- Prevention of Money Laundering: Helps identify suspicious activity and reduce the risk of financial crime.
- Customer Verification: Ensures that financial institutions have accurate customer information.
- Building Trust: Promotes transparency and reliability between customers and financial institutions.
Final Thoughts
The Full Form of KYC is Know Your Customer. KYC can happen online or offline. It identifies and verifies customers’ identities before opening an account, providing a loan, or engaging in any other financial transaction. KYC can be Aadhaar-based or in-person. KYC requires several documents to verify a person’s identity and address.
The process aims to combat financial fraud, terrorist financing, and money laundering. It also complies with various laws and regulations. Businesses and individuals must understand the process, as it may apply to them and is critical to the financial system’s stability.
Frequently Asked Questions (FAQs)
Q1. Why is KYC required?
Answer: KYC verifies customers’ identities, prevents financial fraud, reduces money-laundering risk, and helps financial institutions comply with applicable regulations.
Q2. Can I complete KYC online?
Answer: Yes, you can complete KYC online through supported bank or financial service platforms. Depending on the provider, the process may involve submitting documents, Aadhaar-based verification, or completing video-based verification.
Q3. Is Aadhaar mandatory for KYC?
Answer: No, Aadhaar is not mandatory for every KYC process. Depending on the service and applicable rules, customers may use other officially accepted identity documents or verification methods.
Q4. How can I check my KYC status?
Answer: You can check your KYC status on your bank website or mobile app, or through customer support. For securities market-related KYC in India, you may also check with the relevant KYC Registration Agency (KRA).
Q5. What documents are needed for KYC?
Answer: KYC may require proof of identity, proof of address, a photograph, and other information, depending on the financial service. Accepted documents and verification methods vary. Commonly accepted documents include a passport, driving license, voter ID, and other officially valid documents. PAN may also be required for applicable financial transactions.
Q6. What is the full form of KYC in banking?
Answer: KYC stands for Know Your Customer. It refers to the process banks use to verify customers’ identities and addresses before providing certain financial services.
Q7. What is the difference between KYC and e-KYC?
Answer: KYC is the general process of verifying a customer’s identity, while e-KYC (Electronic Know Your Customer) uses electronic methods to complete identity verification. Traditional KYC may involve physical documents or in-person checks, whereas e-KYC may use digital document submission, electronic identity verification, or video-based procedures.
Recommended Articles
We hope this comprehensive guide to the Full Form of KYC helps you understand what it means, why it matters, and how it works. Check out these recommended articles for more insights into banking, financial security, and related concepts.

