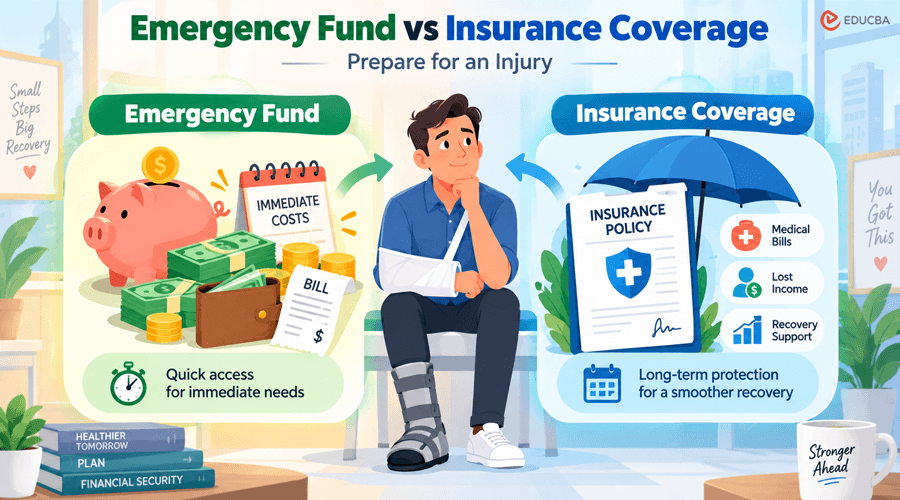
A serious injury hits your finances before it hits your inbox. The ambulance bill, the copay, the missed shift, the rideshare to the follow-up appointment. All of that lands weeks before any insurance check does, and how you handle those first weeks often decides whether the claim itself becomes a second crisis.
Understanding emergency fund vs insurance coverage can help professionals prepare for both the immediate financial shock and the longer recovery period. Two things will carry you through: the cash you can access today and the policies you set up months or years ago.
Cash Reserves Absorb the First Shock
The first thirty to sixty days after an injury come out of your pocket, no matter what coverage you have. Emergency room copays, prescriptions, a rental car, time off before short-term disability kicks in, gas to and from physical therapy. None of it waits for a claim to be adjudicated. This is where liquid savings do their job.
The catch is that most people do not have the cushion they think they do. A sudden injury rarely produces a small bill, and the out-of-pocket costs in the first week alone can strain a thin savings account. Most households end up borrowing, putting it on a card, or letting other bills slide.
If you do not have a reserve built yet, the Consumer Financial Protection Bureau’s emergency fund guide is a plain, practical starting point. Aim for enough to cover essential expenses for several months, kept somewhere you can reach in a day, not tied up in investments or earmarked for a future goal.
Insurance Carries the Longer Tail
Cash gets you through the shock. Insurance gets you through the recovery. If you are out of work for months, no reasonable emergency fund will cover the full income gap, and this is where policies you set up in advance start to matter more than the balance in your checking account.
When comparing emergency fund vs insurance coverage, it is important to understand that they serve different financial purposes.
A simple emergency fund gives you cash right away, while insurance helps cover bigger medical bills, lost income, and other long-term costs.
- Health insurance: Handles medical treatment, but rarely the full bill. Expect deductibles, coinsurance, out-of-network surprises, and gaps for anything the carrier calls elective.
- Short- and long-term disability? It provides part of your income if you cannot work. Short-term picks up after a brief waiting period; long-term takes over if recovery drags on.
- Auto medical payments and PIP: Pay for medical costs after a crash regardless of fault, often faster than a liability claim. Coverage limits vary widely, and many drivers carry far less than a serious injury requires.
- Workers’ compensation: Employer-provided in most cases, covering medical care and a share of lost wages for on-the-job injuries. State insurance regulators typically publish a plain-language overview of the main benefit categories, and most jurisdictions follow the same general structure, even if the numbers differ.
Know What Your Claim Actually Covers Before You Need It
Most people read their policies for the first time after something goes wrong. That is a bad moment to discover a 90-day elimination period or a mileage exclusion. Pull the documents now and confirm the numbers you would actually receive.
- Check your disability replacement rate: Know the percentage of income covered, the waiting period, and the maximum benefit duration.
- Confirm your auto medical limits: Look at medical payments, PIP where applicable, and uninsured motorist coverage. Raise them if a single ER visit would burn through the whole limit.
- Read your workers’ comp notice: Employers must post or provide claim instructions. Know whom to notify and how quickly.
- Keep a claims folder ready: Policy numbers, HR contacts, primary care records, and a running log of any prior injuries. It saves days when a claim actually happens.
When the Numbers Get Serious, Get Help Early
Small claims tend to resolve themselves. Larger ones do not, and the gap between what an insurer offers and what a claim is actually worth can be significant once you factor in lost future earnings, ongoing treatment, and permanent limitations. Adjusters price cases to close them, not to make you whole.
If an injury has meaningfully changed what you can do at work, or if the initial settlement offer feels light against your actual costs, it is usually worth talking to an experienced injury attorney before signing anything. Most work on contingency, so the consultation costs nothing, and the review often surfaces categories of damages that self-represented claimants miss.
Financial preparation is not only about surviving the injury. It is about not accepting a settlement out of desperation because the bills are stacking up.
Understanding emergency fund vs insurance coverage before an accident or injury occurs can give you more control over your finances when you need it most.
Recommended Articles
We hope this guide helps you understand emergency fund vs insurance coverage and prepare financially for an unexpected injury. Explore these recommended articles for more insights on emergency savings, insurance coverage, injury claims, disability benefits, and financial planning.