What is Staple Financing?
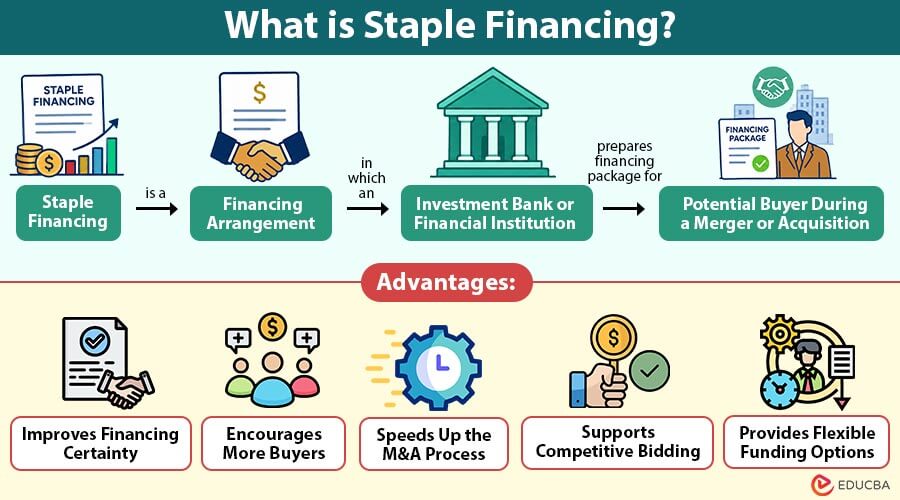
Staple financing is a financing arrangement in which an investment bank or financial institution prepares a financing package for a potential buyer during a merger or acquisition. The financing terms are typically prepared before the transaction is completed and may be offered to qualified bidders.
The term “staple” refers to the idea that the financing package is attached or “stapled” to the transaction. The arrangement can help potential buyers understand how much debt financing may be available and what the expected terms could look like.
Staple financing is commonly used in mergers and acquisitions (M&A), particularly when a seller wants to make the acquisition process more competitive and provide potential buyers with a readily available financing option.
For example, suppose a company is being sold for ₹500 crore. An investment bank may arrange a financing package that allows an eligible buyer to borrow ₹300 crore to fund part of the purchase price. The buyer can then use its own funds for the remaining ₹200 crore, subject to the final transaction terms.
Table of Contents:
- Meaning
- Importance
- Working
- Types
- Advantages
- Risks
- Example
- Difference
- Factors to Consider Before Using Staple Financing
Key Takeaways:
- Staple financing provides potential buyers with pre-arranged funding during mergers and acquisitions, improving financing certainty.
- It can encourage more bidders by reducing financing barriers and supporting competitive acquisition processes.
- Buyers should carefully evaluate interest rates, fees, covenants, leverage, repayment terms, and alternative financing options.
- Staple financing does not guarantee funding, as final approval depends on lender assessments and transaction conditions.
Why is Staple Financing Important?
Staple financing can make a mergers and acquisitions transaction more efficient by reducing uncertainty around acquisition funding.
1. Improves Financing Certainty
Potential buyers can see that a financing structure is already in place. This makes it easier to estimate available funding and prepare a bid.
2. Encourages More Bidders
A ready financing package can reduce financing barriers for potential buyers. More bidders may be willing to participate when they know that acquisition financing is potentially available.
3. Supports Competitive Bidding
Staple financing can encourage competition among buyers. Buyers can focus on the target’s value rather than spending excessive time arranging financing before submitting an initial bid.
4. Speeds Up the Transaction
Because the financing structure has already been prepared, some initial financing work may be completed before the buyer is selected. This can potentially shorten the time needed to complete the acquisition.
5. Helps Buyers Assess their Funding Capacity
A potential buyer can compare the proposed financing with its available equity and determine whether the transaction is financially feasible.
How Does Staple Financing Work?
Staple financing generally involves several parties, including the seller, investment bank, lenders, and potential buyers.
The process usually follows these steps:
1. Seller Decides to Explore Financing
The seller begins selling the business through a negotiated transaction or competitive bidding process. To make the transaction easier for potential buyers to finance, the seller may ask an investment bank to arrange staple financing.
2. Investment Bank Structures the Financing
The investment bank evaluates the target company’s financial position, cash flows, assets, debt capacity, and business prospects. Based on this assessment, it develops a potential financing package. The package may include information about the proposed loan amount, interest rate, maturity, repayment structure, fees, and other lending conditions.
3. Financing Package is Offered to Potential Buyers
Qualified buyers receive information about the financing package. Buyers can evaluate whether the proposed debt structure suits funding the acquisition. Importantly, a buyer does not necessarily have to use the staple financing. It may arrange financing independently if it can obtain more attractive terms from another lender.
4. Buyer Submits an Acquisition Bid
Financing availability can help potential buyers determine how much they can afford to offer. A buyer may use the financing package as a reference when preparing its acquisition proposal.
5. Financing is Finalized
Once a buyer is selected, the parties negotiate the final financing terms. The initial staple financing package may be modified based on the buyer’s credit profile, transaction structure, market conditions, and due diligence findings.
6. Acquisition is Completed
After the buyer finalizes the financing arrangements and other transaction conditions, it completes the acquisition using the agreed combination of debt and equity.
Types of Staple Financing
Staple financing can take different forms depending on the transaction and the buyer’s funding requirements.
1. Senior Debt Financing
Senior debt has priority over subordinated debt when the borrower repays its obligations. It generally carries lower interest costs because lenders have a higher priority claim on the borrower’s assets and cash flows.
2. Mezzanine Financing
Mezzanine financing combines debt and equity characteristics. It generally costs more than senior debt because lenders assume greater risk. It can be useful when the buyer needs additional funding beyond the amount available through senior loans.
3. Leveraged Financing
Leveraged financing uses significant debt to fund an acquisition. The target company’s future cash flows may support the repayment of the acquisition-related debt. This structure is particularly relevant in leveraged buyouts where the buyer seeks to finance a substantial portion of the purchase price with borrowed funds.
4. Bridge Financing
Bridge financing provides temporary funding until the buyer obtains permanent financing or completes another funding transaction. It can help buyers move quickly when an acquisition requires immediate capital.
Advantages of Staple Financing
The following are the key advantages of staple financing:
1. Improves Financing Certainty
Buyers have a preliminary financing package, making it easier to assess funding capacity and prepare bids.
2. Encourages More Buyers
Ready access to potential acquisition financing can reduce funding barriers and encourage more buyers to participate.
3. Speeds Up the M&A Process
Since financing arrangements are prepared in advance, buyers may spend less time developing an initial financing structure.
4. Supports Competitive Bidding
A readily available financing option allows buyers to focus more on the target company’s value and submit competitive offers.
5. Provides Flexible Funding Options
Buyers can use the staple financing package or compare it with financing from other lenders before deciding.
Risks of Staple Financing
Despite its benefits, staple financing also has certain risks.
1. Potential Conflict of Interest
The arranging bank may finance the buyer while advising on the sale, creating potential conflicts. Clear disclosures and safeguards can help manage them.
2. Financing May Be Expensive
The proposed financing package may carry higher interest rates or fees than alternatives. Buyers should compare terms from other lenders before accepting financing.
3. Terms May Change
Initial financing terms are not always final. Market conditions, interest rates, buyer creditworthiness, and target performance can influence the final financing arrangement.
4. Increased Financial Leverage
Heavy reliance on debt can create significant repayment obligations. High leverage increases financial risk, especially when the acquired company’s cash flows weaken unexpectedly.
5. Not Suitable for Every Transaction
Staple financing may be unnecessary for smaller acquisitions or buyers with sufficient cash. Established financing relationships may offer simpler, more suitable alternatives.
Example of Staple Financing
Consider a company that is being offered for sale at ₹1,000 crore.
The seller’s investment bank arranges a staple financing package that provides potential buyers with up to ₹600 crore of acquisition debt. The remaining ₹400 crore would need to come from the buyer’s equity or other sources.
Three companies submit bids for the target.
- Buyer A uses the proposed staple financing and contributes ₹400 crore in equity.
- Buyer B uses ₹500 crore of staple financing and contributes ₹500 crore in equity, subject to lender approval and final terms.
- Buyer C obtains financing independently from another lender and decides not to use the staple package.
This example shows that staple financing provides a potential funding option but does not necessarily require every buyer to use the financing offered with the transaction.
Difference Between Staple Financing and Traditional Acquisition Financing
The following table highlights the key differences between staple financing and traditional acquisition financing.
| Feature | Staple Financing | Traditional Acquisition Financing |
| Financing Arrangement | Prepared alongside the sale process | Arranged separately by buyer |
| Timing | Usually available during bidding | Often begins after buyer’s financing strategy is established |
| Main Purpose | Facilitate transaction financing | Meet buyer’s specific funding requirements |
| Buyer Choice | Buyer may accept or seek alternatives | Buyer generally arranges its own financing |
| Transaction Speed | Can potentially accelerate financing | May require additional preparation |
| Competition | Can encourage more bidders | Depends on each buyer’s financing capacity |
Factors to Consider Before Using Staple Financing
Before accepting staple financing, buyers should carefully evaluate the financing structure.
1. Interest Rate
Compare the proposed interest rate with alternative financing options to determine whether the borrowing cost is competitive and financially reasonable.
2. Fees
Carefully review arrangement, commitment, transaction, and other financing fees to understand the total cost of the proposed financing package.
3. Debt Maturity
Understand when the debt becomes due and assess whether refinancing could be necessary before the acquisition generates sufficient cash.
4. Repayment Requirements
Examine scheduled repayments, cash sweep provisions, and other requirements to determine their potential impact on available cash flows.
5. Financial Covenants
Review financial covenants and restrictions that could limit the company’s ability to borrow, invest, operate, or make strategic decisions.
6. Leverage
Assess whether the proposed debt level remains sustainable based on expected cash flows, earnings, and the company’s ability to service debt.
7. Alternative Financing
Compare staple financing with options from banks, private credit providers, and other lenders to identify potentially better terms and flexibility.
Final Thoughts
Staple financing can simplify mergers and acquisitions transactions by providing pre-arranged funding, encouraging buyer participation and competitive bidding. However, buyers should carefully compare costs, terms, covenants, leverage, and alternatives. Transparent structuring and appropriate safeguards can help manage conflicts of interest and ensure financing supports transaction objectives.
Frequently Asked Questions (FAQs)
Q1. Who provides staple financing?
Answer: Staple financing is typically arranged by an investment bank or financial institution that structures a potential financing package for qualified buyers.
Q2. Is staple financing available to every potential buyer?
Answer: Not necessarily. Access may depend on the transaction process, buyer eligibility, lender requirements, confidentiality arrangements, and other conditions.
Q3. Does staple financing guarantee that a buyer will receive the loan?
Answer: No. A proposed financing package does not necessarily guarantee funding. Final approval may depend on due diligence, lender assessments, documentation, and transaction conditions.
Q4. Can a buyer negotiate the terms of staple financing?
Answer: Yes. Once a buyer is selected, the financing terms may be negotiated and adjusted based on the buyer’s circumstances and the final transaction structure.
Recommended Articles
We hope that this EDUCBA information on “Staple Financing” was beneficial to you. You can view EDUCBA’s recommended articles for more information.