The price you see on a similar car is not necessarily what a lender could recover if it had to be sold. When you use a car as security for a short-term loan, understanding car realisable value can help explain why a vehicle with a high retail price may still support a lower loan amount. Understanding that gap helps you see why a vehicle valued highly in the retail market may support a lower loan amount.
Market Price is Only the Starting Point
A market price usually reflects what comparable vehicles are being advertised or sold for under ordinary conditions. It can provide a useful reference point, but it does not automatically represent what you could recover quickly from your particular vehicle. If you have been searching online for ways to “secure a loan against my car based on its value”, it is worth understanding what that value actually represents in a lending context.
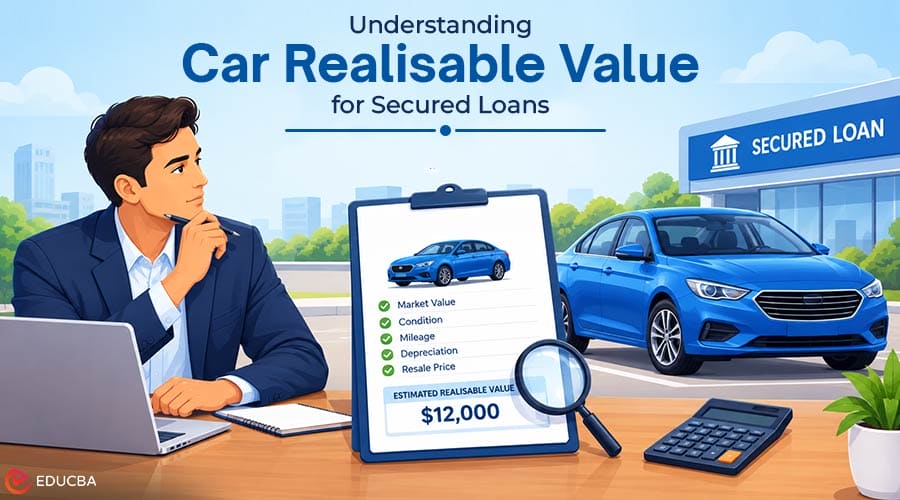
Rather than relying solely on the advertised prices of similar cars, an assessment may consider your vehicle’s condition, specifications, kilometers traveled, and likely resale demand. These factors help establish a more realistic figure for what the vehicle could produce if you needed to sell it.
What is Car Realisable Value?
Car realisable value is what your car could reasonably produce when converted into cash. It therefore accounts for the practical circumstances surrounding a future sale rather than relying solely on an ideal selling price. A private seller may advertise a vehicle for several weeks while waiting for the right buyer. A lender assessing security usually needs a more dependable figure. The resulting value may sit below the best possible retail price because certainty and saleability matter alongside price.
Selling Costs Reduce the Recoverable Amount
The amount received from a vehicle sale is not always the same as the amount ultimately recovered. Inspection, transport, administration, preparation and selling costs may reduce the net proceeds. These deductions help explain why a car advertised for a particular price may have a lower realisable value. The relevant question is not only what a buyer might pay but also what remains after accounting for the costs of completing the sale. In valuation terms, the focus is on what you can realistically recover.
Sale Timing Changes What the Car May Realise
Time is another reason price and realisable value can differ. Achieving the highest possible price generally requires finding a buyer willing to meet it, and that process may take time. Where a faster sale is required, the realistic selling price may be lower. Valuers therefore consider liquidity, which measures how readily they can convert an asset into cash without a substantial loss in value. Popular vehicles with strong second-hand demand may retain a smaller gap between market and realisable values than specialized or slow-moving models.
Depreciation Also Affects Future Recovery
Vehicle values rarely remain static. Age, kilometers traveled, model changes, and shifts in used car demand can all contribute to depreciation over time. A secured loan assessment may consequently consider not only what your car appears to be worth today, but also whether its value could change during the loan period. Allowing for that possibility creates a buffer between an optimistic selling price and the amount reasonably expected to remain recoverable.
Condition Can Widen the Value Gap
Two cars of the same make, model, and year can have noticeably different realisable values. Service history, mechanical condition, body damage, tire condition, kilometers traveled, and optional equipment can all affect buyer demand.
Minor problems may also have a greater impact on realisable value than you expect. A defect you might tolerate while driving could discourage buyers or require repair before resale. Assessing the individual vehicle therefore matters more than relying on an average model price.
Focus on What the Car Can Realistically Return
Understanding car realisable value means viewing your car as an asset you may need to convert into cash rather than simply asking what similar vehicles sell for. Condition, demand, selling costs, timing and depreciation can all create a gap between those figures. Once you recognize that difference, it becomes easier to understand why the amount attributed to your car for secured lending may be lower than the retail prices you see in the market.
Recommended Articles
We hope this guide to car realisable value helps you better understand vehicle valuations for secured lending. Check out these recommended articles for more insights into car finance, valuations, and related topics.