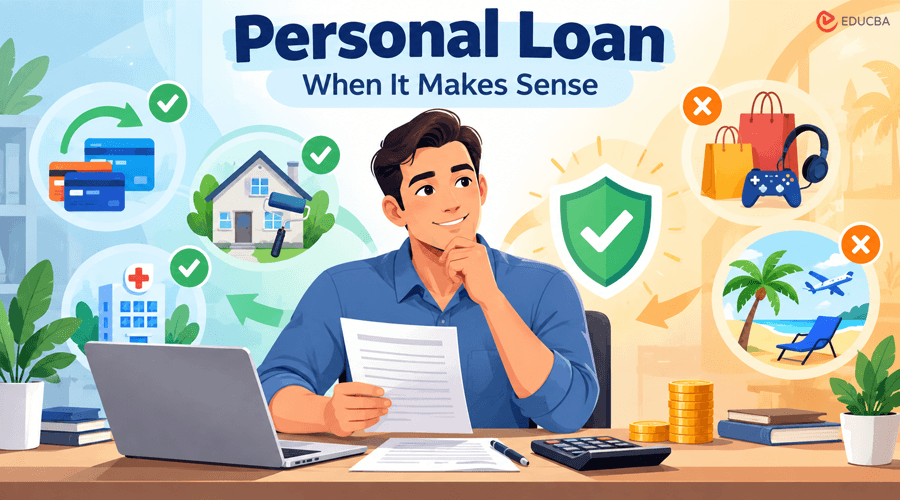
A personal loan is one of the few credit products that’s genuinely neutral. It is not inherently sensible like a mortgage or inherently expensive like a cash advance. Whether it is a good idea depends almost entirely on what you are replacing with it. If you use it to consolidate three high-rate debts into one lower-rate repayment, it is a straightforwardly good decision. If you use it to fund a holiday you would otherwise skip, it is an expensive way to bring forward something you could have saved for.
Same product, opposite outcomes. Australians are borrowing a fair amount this way. The Australian Bureau of Statistics recorded $9.7 billion in new fixed-term personal finance commitments in the June quarter of 2026, up 7.1% on the same quarter a year earlier. Road vehicles accounted for $4.7 billion of that, with the balance spread across personal investment, travel, household goods and other purposes. Here is how to work out which side of the line your situation falls on.
Secured or Unsecured, and Why It Changes the Price?
An unsecured personal loan is not tied to an asset. You borrow, you repay, and if you do not, the lender pursues the debt but has nothing specific to seize. A secured loan is attached to something, usually a vehicle.
ASIC’s Moneysmart guidance on secured and unsecured personal loans puts the trade plainly: security buys you a lower rate, and it gives the lender the right to sell the asset if you cannot pay. The rate gap between the two is usually substantial. If you are buying a car, boat or caravan, securing the loan against it is almost always the cheaper structure, and the asset is at risk either way in practical terms.
Where Unsecured Makes Sense?
Consolidating existing debt, funding a renovation, covering medical costs or paying for a wedding are all cases where there is no asset to secure against. Unsecured is the only option, and the question becomes which lender prices it best.
Unplanned costs sit in the same category, and they are the ones people are least prepared for. Veterinary and end-of-life care for a pet is a common example: what euthanasia and aftercare cost in Australia runs into four figures once you add both, and the bill arrives with no notice and no window to save for it.
What the Rate Difference is Worth in Dollars?
Rates on unsecured personal loans vary widely depending on your credit profile and the lender. On a $20,000 loan over five years, here is what that spread costs.
| Interest Rate | Monthly Repayment | Total Interest |
| 8.99% | $415.07 | $4,904.20 |
| 12.99% | $454.96 | $7,297.55 |
| 17.99% | $507.76 | $10,465.59 |
Calculated on $20,000 over 60 months, fees excluded.
The difference between the top and bottom row is $5,561, which is more than a quarter of the amount borrowed. For many borrowers, it is also the difference between shopping around and accepting the first approval. Compare the comparison rate, which includes the fees, rather than the advertised rate.
The Consolidation Case, Done Properly
Debt consolidation is the strongest argument for a personal loan and the easiest to get wrong. The logic is sound: replace several high-rate debts with one lower-rate loan, pay less interest, and have one repayment date instead of four. It works when three conditions hold. The new rate is genuinely lower than the weighted average of what you are replacing.
The term is not so much longer that you pay more overall despite the lower rate. Moreover, you close the accounts you paid off rather than leaving them open. That third condition is where consolidation fails most often. Clearing three credit cards into a personal loan and then running the cards back up leaves you with four debts instead of three.
How Long Should the Term Be?
Long enough that the repayment is comfortable, short enough that you are not still paying in 2033 for something bought this year. Stretching a term always lowers the repayment and always raises the total interest. If the only way the repayment works is a seven-year term on a consumer purchase, that is information about affordability rather than a structuring problem to solve.
What Lenders Look At?
The assessment is more consistent across lenders than most people expect, even though the outcomes vary.
- Credit file: Defaults, judgments, and repayment history. Recent credit inquiries also show up, and a run of them in a short period reads badly.
- Income stability: Not just the amount but how long you have been earning it and in what form. PAYG with tenure is the simplest case.
- Existing commitments: Credit card limits are usually assessed at the limit rather than the balance. Buy now, pay later accounts count. So does HECS.
- Living expenses: Lenders apply a benchmark and compare it against what you declare. Understating expenses does not help, because the benchmark overrides you.
Brokers arranging personal loans across a lender panel are mostly trading on knowing which of these each lender weights heaviest, which is why one application through a panel usually beats four applications made individually.
The Fees That Do Not Show in the Advertised Rate
Two loans at the same headline rate can cost meaningfully different amounts, and the gap sits in the fee schedule.
- Establishment fee: Charged once at the start, commonly a few hundred dollars, sometimes waived on request.
- Monthly account fee: Small in isolation and substantial over a term. Ten dollars a month across five years is $600, which on a $20,000 loan is equivalent to roughly a full percentage point of rate.
- Early repayment or discharge fee: This one matters if you expect to clear the loan ahead of schedule. Fixed rate loans sometimes carry a break cost calculated on the remaining term.
- Late payment fee: Worth knowing, and worth setting up a direct debit to avoid.
All of these are captured in the comparison rate, which is why it is the only figure worth comparing across lenders.
Can You Pay a Personal Loan Off Early?
Usually, but check the contract rather than assuming. Variable rate loans generally allow unlimited extra repayments without penalty. Fixed rate loans sometimes cap them or charge to break the term. If you have any chance of a bonus, a tax refund, or an inheritance going toward the loan, early repayment terms matter more than a small rate difference.
What to Do If the Repayment Becomes Difficult?
Tell the lender before you miss a payment, not after. Licensed credit providers must consider hardship requests, and options include reduced repayments for a period, a temporary pause, or extending the term. A hardship arrangement agreed in advance is handled very differently to a missed payment reported to your credit file. The difference persists for years, so the call is worth making early.
The Test Worth Applying
Before you apply, answer one question honestly: is this loan replacing a more expensive debt, or creating a new one? If it is replacing something, the maths usually works, and the job is finding the best rate. If it is creating something new, the real question is whether the purchase justifies paying for it twice over, once in principal and again in interest.
Either way, get the comparison rate and the total amount payable in writing, check whether extra repayments are allowed without penalty, and make sure the term matches how long you will actually benefit from whatever you are borrowing for.
Recommended Articles
We hope this guide helps you understand personal loans, their costs, and when they make financial sense. Explore our recommended articles for more insights on personal finance, debt consolidation, loan management, interest rates, and financial planning.