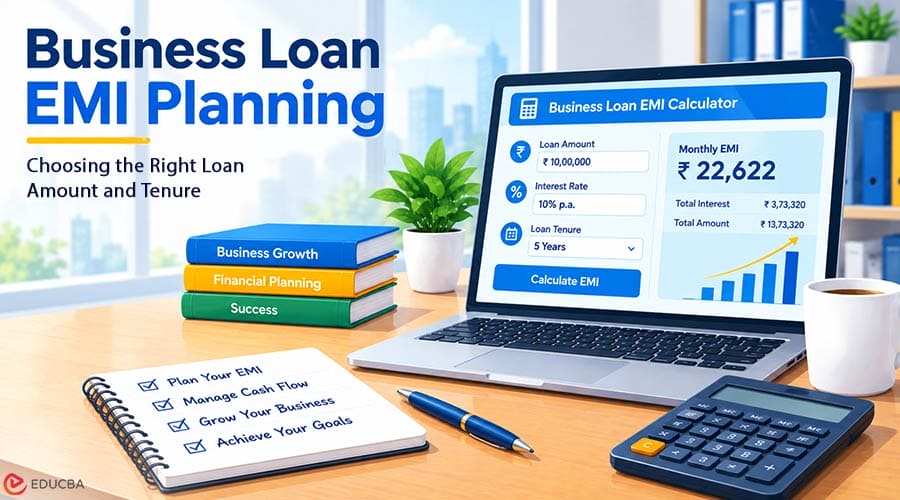
Running a business often requires regular investment in inventory, equipment, staff, technology, or expansion. A business loan can fund these needs, but repayments should fit comfortably within the business’s cash flow. Business loan EMI planning can help you understand the monthly financial commitment and avoid unnecessary pressure on working capital. A business loan EMI calculator makes this easier by showing how the loan amount, interest rate, and tenure can affect your repayment. With a clear EMI plan, business owners can borrow responsibly and manage their finances more effectively.
Why Business Loan EMI Planning Matters?
Business revenue can fluctuate, while loan EMIs remain a regular financial commitment. An EMI that seems manageable during a strong sales period may become difficult during a slower period.
Good EMI planning helps you consider loan repayments alongside regular expenses such as:
- Employee salaries
- Supplier payments
- Rent and utilities
- Inventory purchases
- Marketing expenses
- Working capital needs
Before borrowing, assess how the proposed EMI fits into your current cash flow and future business plans.
Key Factors to Consider During Business Loan EMI Planning
When planning your business loan EMI, consider the following key factors to ensure the repayment fits your cash flow and overall financial requirements:
1. Review Your Business Cash Flow
Start by assessing your business’s monthly income and expenses. Review sales, operating expenses, supplier payments, salaries, existing EMIs, and other regular costs.Also consider seasonal changes in revenue. A retail business may see higher sales during festive periods, while a service business may receive payments after completing projects. Your EMI should remain manageable even when revenue is lower than usual. A clear view of your cash flow can help you decide how much you can reasonably allocate towards loan repayment.
2. Calculate Your EMI Before Borrowing
Before you apply for business loan financing, estimate the EMI you may need to pay each month. A business loan EMI calculator can help you compare different loan amounts, interest rates, and repayment tenures.
You generally need to enter:
- Loan amount
- Applicable interest rate
- Loan tenure
The calculator can estimate your monthly EMI and may also show total interest and the total repayment amount. Try different combinations to understand how changing the loan amount or tenure affects your repayment. For instance, Tata Capital’s business loan EMI calculator can show how borrowers can assess different repayment scenarios before deciding to borrow.
3. Choose a Loan Amount Based on Your Requirement
Your eligible loan amount may be higher than what your business actually needs. Taking a larger loan simply because it is available can increase your EMI and overall borrowing cost.
First, define the purpose of the funds. You may need financing for:
- Purchasing machinery
- Expanding a business location
- Buying inventory
- Hiring additional staff
- Upgrading technology
- Managing working capital
Once you know the required amount, avoid unnecessary borrowing. Taking only what you need can make repayment easier to manage.
4. Select a Suitable Loan Tenure
Loan tenure affects both your monthly EMI and total interest payable. A longer tenure spreads repayment over more months, which can reduce the monthly EMI. However, it may increase the total interest paid over the loan period. A shorter tenure generally means a higher EMI but can reduce the overall interest cost.
When comparing tenures, consider:
- Monthly cash flow
- Expected business income
- Existing financial commitments
- Total interest payable
- Preferred repayment period
The right tenure should balance monthly affordability with the overall cost of borrowing.
5. Match the EMI With Your Revenue Cycle
Businesses do not always earn the same amount every month. Understanding your revenue pattern matters when planning repayments. A manufacturer may have longer payment cycles, while a retailer may experience seasonal changes in sales.
A project-based business may also receive large payments only after completing specific assignments. Consider weaker revenue periods when assessing EMI affordability. Planning only around your best-performing months could make repayments difficult during slower periods.
6. Account for Existing Financial Commitments
Review your current financial obligations before taking another loan. These may include existing business loans, equipment financing, credit facilities, and other repayment commitments. Adding a new EMI without considering existing obligations can reduce the funds available for daily operations. Look at your total monthly debt responsibility rather than assessing the new EMI separately. This helps you determine whether additional borrowing suits your current financial position.
7. Maintain a Repayment Buffer
Unexpected events can affect business cash flow. Customer payments may be delayed, sales may fall temporarily, or operating expenses may increase. Maintaining a reasonable cash reserve can provide a buffer during such situations.
It can help you continue meeting EMI obligations without immediately affecting essential business expenses. Avoid using all available funds for expansion and leave room for unexpected costs. A repayment buffer can make your financial plan more stable.
8. Consider the Purpose and Expected Benefit
How effectively a business loan supports your business depends on how you use the funds. Before borrowing, identify the specific purpose and consider how the investment could support your business operations or growth.
For instance, new equipment may increase production capacity, while additional inventory can help you meet rising customer demand. Working capital can also help manage regular business expenses during periods of uneven cash flow. Understanding the expected outcome can help you decide whether the loan amount and EMI match your business needs and financial plans.
9. Review the Interest Rate and Other Charges
The interest rate is an important part of your borrowing cost. The applicable rate may depend on factors such as your credit profile, business performance, income, loan amount, tenure, and lender-specific criteria. Do not assess a loan only by its EMI.
Also review applicable charges, which may include:
- Processing fees
- Documentation charges
- Prepayment charges
- Foreclosure charges
- Other applicable fees
Understanding these costs gives you a clearer picture of the total financial commitment.
10. Compare Different Repayment Scenarios
Before finalizing your loan, compare different combinations of loan amount and tenure. This helps you understand the trade-off between monthly affordability and overall borrowing cost.
For example:
- Higher amount with shorter tenure: This can result in a higher EMI but may reduce the total interest cost.
- Moderate amount with medium tenure: This may balance funding needs with repayment comfort.
- Lower amount with longer tenure: This may reduce the monthly EMI but can increase the total interest payable.
Comparing these scenarios can help you choose a repayment structure that suits your business, rather than simply selecting the lowest EMI.
11. Treat EMI as a Regular Business Expense
Once you take a loan, include the EMI in your regular business budget. Consider it alongside salaries, rent, utilities, supplier payments, taxes, and other operating costs. This makes the repayment obligation part of your routine financial planning. Before making another major expense or investment, check whether your business can manage it alongside the existing EMI.
A Simple EMI Planning Checklist
Before you apply for business loan financing, use this checklist:
- Define your requirement: Identify exactly why you need the funds.
- Review cash flow: Consider regular income, expenses, and seasonal changes.
- Estimate your EMI: Use a calculator to compare repayment scenarios.
- Choose a suitable tenure: Balance monthly affordability with total interest.
- Check the complete cost: Review interest and applicable charges.
- Maintain a buffer: Keep funds available for unexpected business expenses.
- Monitor repayment: Review your loan and cash flow regularly.
Final Thoughts
Effective business loan EMI planning helps business owners use borrowed funds without putting unnecessary pressure on daily operations. Before you apply for business loan financing, assess your cash flow, define your funding requirement, and compare different repayment scenarios.
Using a business loan EMI calculator can make it easier to understand how the loan amount, interest rate, and tenure affect your monthly commitment. The goal is not simply to find the lowest EMI, but to choose a repayment structure your business can manage comfortably while continuing to meet its operating and growth needs.
Recommended Articles
We hope this comprehensive guide to business loan EMI planning helps you manage your loan repayments and make informed borrowing decisions. Check out these recommended articles for more insights and strategies to strengthen your business finances.