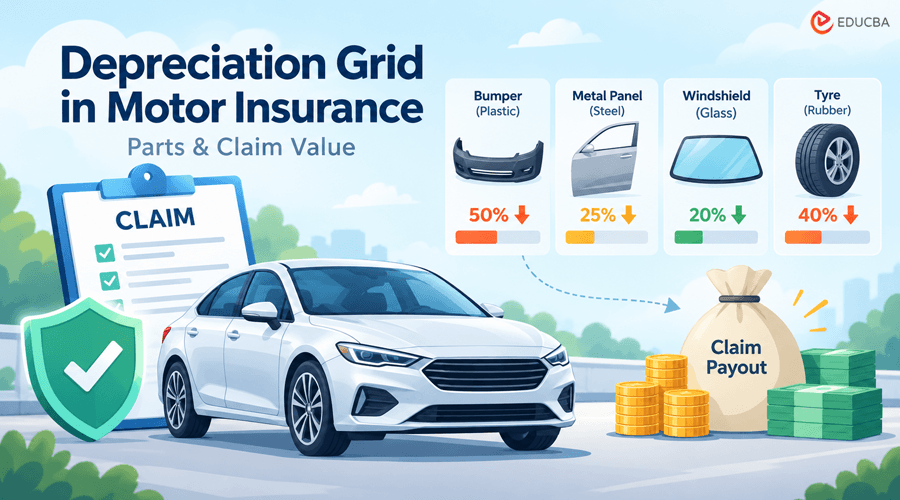
Anyone who files a car insurance claim and receives a smaller payout than expected may have encountered the Depreciation Grid in Motor Insurance without realizing it. It is one of those background mechanics of motor insurance that quietly shapes how much you actually receive, yet very few policyholders understand it until a claim brings it front and center. Here is a plain explanation of what this grid is, how it values different parts, and why it matters more than most people assume.
Why Depreciation Shows Up in Every Claim?
Your insurer does not pay the full retail price of a new part when you file a claim to repair or replace damaged parts. Car parts lose value due to wear and age. That is why most insurers apply a depreciation deduction to reflect that reality. The rate of this deduction follows a standardized structure known as the Depreciation Grid in Motor Insurance.
Understanding how depreciation works can help you estimate your potential claim payout and understand why the insurer may not cover the entire replacement cost of a damaged part.
What the Depreciation Grid Actually Is
The Depreciation Grid in Motor Insurance refers to a standardized table that sets fixed depreciation percentages. It generally depends on the vehicle’s age and the type of part being replaced. The grid creates consistency across the industry, so insurers apply similar depreciation rates to the same parts on vehicles of similar age. It removes a lot of the ambiguity that used to exist around claim settlements.
The grid provides a framework that determines how much depreciation insurers deduct from the value of eligible parts during a motor insurance claim.
How the IRDAI Grid Sets the Standard?
In India, the Insurance Regulatory and Development Authority of India (IRDAI) guides the motor insurance depreciation framework and sets the depreciation percentages insurers follow. Because the Depreciation Grid in Motor Insurance follows a standardized structure rather than individual insurer rules, policyholders can understand how depreciation may affect their claim settlement before filing a claim. However, the actual claim settlement can also depend on the terms, conditions, exclusions, deductibles, and add-ons included in the individual insurance policy.
Age-Based Slabs Explained
The Depreciation Grid in Motor Insurance works in slabs based on the vehicle’s age. A brand-new car, typically under six months old, usually sees little or no depreciation applied. As the vehicle crosses six months, then one year, then moves into the two- to three-year range and beyond, the depreciation percentage climbs in stages.
By the time a vehicle crosses five years, depreciation on several part categories reaches a substantially higher rate than a newer vehicle would see for the same part. This age-based structure means that the same damaged part can have a different depreciation deduction depending on how old the insured vehicle is.
How Are Different Parts Valued Differently?
One of the more surprising aspects of the Depreciation Grid in Motor Insurance is that it does not treat all parts the same way, even parts replaced under the same claim on the same vehicle. The applicable depreciation can vary according to the material and category of the part. Understanding these differences can make the claim settlement easier to interpret.
Rubber, Plastic, and Fiber Parts
Parts made of rubber, plastic, and fiberglass depreciate faster under the grid compared to metal components. Items like bumpers, plastic trims, and rubber seals can have depreciation rates of up to fifty percent even on relatively young vehicles because these materials wear out faster. As a result, replacing several plastic or fiber components during a single accident can lead to a noticeable depreciation deduction under the Depreciation Grid in Motor Insurance.
Metal Parts and Glass
Metal components often depreciate more slowly than plastic or rubber parts. This also reflects their longer usable life. Glass parts, such as windshields, are usually treated separately, often with their own fixed depreciation rate that does not always follow the same slab structure as the rest of the vehicle. Knowing this distinction helps explain why a claim involving a cracked bumper and a cracked windshield on the same car can show two very different depreciation deductions.
Why Zero Depreciation Cover Exists Because of This Grid?
This system is exactly why zero depreciation cover became such a popular add-on. Once you understand how steeply plastic and fiber parts depreciate, even on a car that is only two or three years old, it becomes clear why paying extra to skip that deduction entirely can make a real difference at claim time, particularly for parts that are expensive to replace and depreciate quickly under the standard grid.
How Does the Depreciation Grid in Motor Insurance Affect Your Payout?
When processing your claim, the garage or surveyor identifies the parts that need replacement, calculates their costs, and applies the relevant depreciation percentage based on your vehicle’s age. After deducting the policy excess, the insurer pays the remaining amount unless your zero depreciation add-on covers the eligible parts.
Checking Your Policy Before You Ever Need a Claim
It is worth taking a few minutes to check car insurance online through your insurer’s portal to see whether your current plan includes zero depreciation cover, and if not, what it would cost to add it based on your vehicle’s age. Doing this ahead of time, rather than discovering the gap during a claim, gives you a much clearer picture of what you are actually protected against.
Why Cashless Car Insurance Makes This Easier to Navigate?
Filing a claim through a cashless car insurance network garage tends to make the depreciation calculation more transparent, since the garage works directly with your insurer using the same standardized grid, and the settlement details are usually shared with you as part of the process rather than left for you to piece together later. This does not eliminate depreciation, but it makes the process easier to follow and verify.
A Few Things Worth Remembering
The Depreciation Grid in Motor Insurance is not something insurers invented arbitrarily to reduce payouts. It provides a standardized approach to valuing parts based on factors such as vehicle age and the type of part involved. Understanding how your vehicle’s age and the part involved affect your eventual payout matters.
This knowledge can help you decide whether an add-on like zero depreciation cover is worth including in your policy. The question becomes especially relevant as your car moves further away from its original purchase date. By understanding the Depreciation Grid in Motor Insurance, you can better interpret claim calculations, anticipate depreciation-related deductions, and review your coverage before you actually need to file a claim.
Recommended Articles
We hope this guide helps you understand the Depreciation Grid in Motor Insurance and how it affects car parts and claim payouts. Explore our recommended articles for more insights on motor insurance, car insurance claims, zero depreciation cover, vehicle insurance, and insurance add-ons.